Innovative Tax Relief
Attorneys, CPAs & Enrolled Agents · All 50 states

When to hire a tax attorney, and when an Enrolled Agent is enough.

Updated

Most people searching for a tax attorney do not actually need one. Attorneys, CPAs and IRS Enrolled Agents all hold unlimited practice rights before the IRS, and for most collection cases the Enrolled Agent is the person who works that file every day. Here is how to tell which credential your case really calls for.

The essentials, at a glance

Three credentials, equal IRS rights
Attorney, CPA and Enrolled Agent all hold unlimited practice rights before the IRS under Circular 230.
When an attorney is the answer
Tax Court petitions, criminal exposure, and any matter where attorney-client privilege matters.
When an EA usually is
Collection work: garnishment and levy releases, installment agreements, offers, penalty relief.
What ITR is
A tax resolution firm, not a law firm. Tax attorneys are on staff alongside CPAs and Enrolled Agents.
Form 2848 for your authorized IRS matters Unlimited IRS practice rights, every state Typically a 5-minute callback in business hours Free, confidential consultation

Free consultation

Get help with an IRS wage garnishment

During business hours, you can typically expect a callback within 5 minutes. Free, confidential, no obligation.

By clicking “Get my free consultation,” you provide the consent below and agree to our Terms of Use and Privacy Policy.

By clicking “Get my free consultation,” I am providing my express written consent to be contacted by Innovative Tax Relief LLC at the phone number and email address provided above, including via autodialed and/or prerecorded voice calls, to discuss the products and services offered, including telemarketing sales calls and informational calls made in response to my request. I confirm that I am authorized to receive calls at the number provided. I also agree to receive emails from Innovative Tax Relief, including emails to my mobile device. I waive any registration on any state, federal, or corporate Do Not Call registry for the purposes of these communications. I understand that consent is not a condition of purchase and that message and data rates may apply. I also agree to receive recurring text messages from Innovative Tax Relief to provide me support and information. Reply STOP to opt out. Reply HELP for help. Message frequency varies. Message and data rates may apply. Carriers are not liable for delayed or undelivered messages. See our Privacy Policy and SMS Terms and Conditions.

01 · How this works

What IRS representation actually requires.

Start with the part most people get wrong. Innovative Tax Relief is a tax resolution firm, not a law firm. Our team includes tax attorneys alongside CPAs and IRS Enrolled Agents, and all three of those credentials hold unlimited rights to practice before the IRS under Treasury Circular 230. When your case needs an attorney, you get an attorney. When it needs an Enrolled Agent, you get the person who works collection cases every single day.

For federal IRS representation, your representative generally does not need to live in your state. An attorney in good standing, a federally licensed Enrolled Agent, or a qualified CPA can represent taxpayers before the IRS across state lines. Court appearances and state-law advice involve separate requirements. We represent clients before the IRS in all 50 states, and if you are still searching for tax relief near me, relevant credentials and case experience matter alongside location.

Representation puts a credentialed professional in charge of authorized communications, gives them time to review your IRS account transcripts before responding, and helps get a proposal into the format the IRS requires. Honest answers remain essential. Preparing the supporting records and the context of your case also helps avoid mistakes when responding to a Revenue Officer.

The rest of this page covers when a tax debt attorney is the right call and when another credential is, what happens in a wage garnishment case, how the 21-day bank levy hold works, what an IRS audit help and audit defense engagement looks like, and what to check before you hire anybody. If you would rather just talk it through, the free consultation is the diagnostic step.

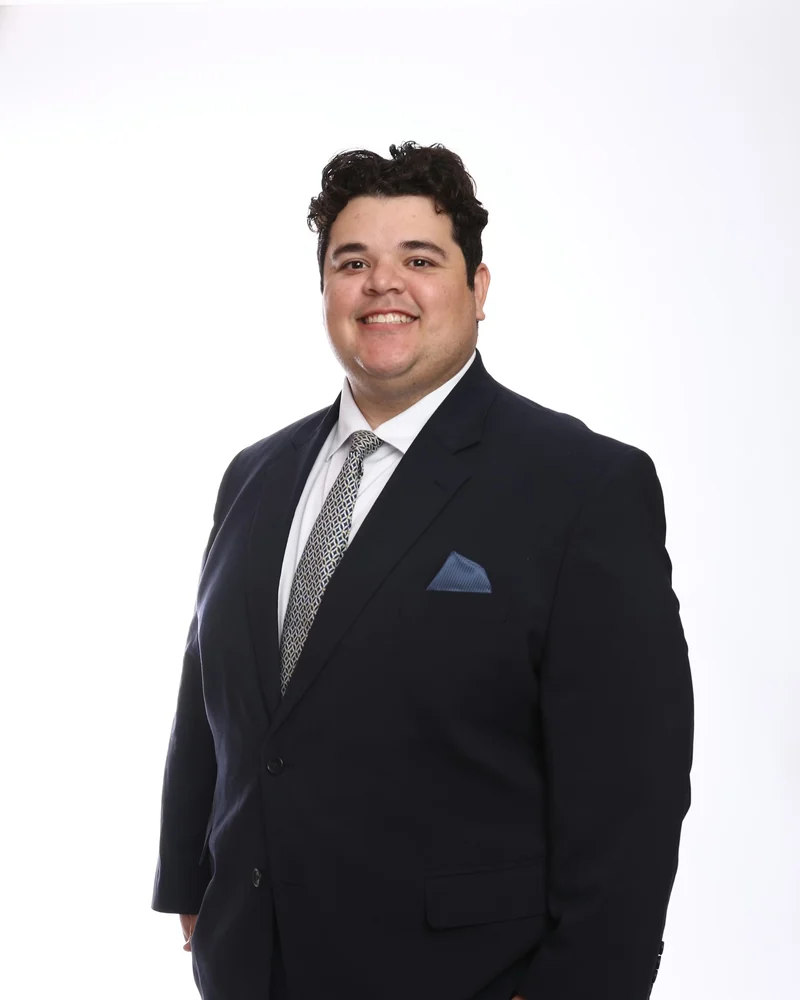
Ryan Colón, Florida-licensed tax attorney at Innovative Tax Relief

Ryan Colón

FL Tax Attorney · U.S. Tax Court

Florida-licensed tax attorney and U.S. Tax Court admitted advocate. JD from Florida State University. Negotiates directly with the IRS to defend clients from aggressive collection action.

Our credentials and accreditations →

02 · Attorney vs EA vs CPA

Tax debt attorney, CPA, or Enrolled Agent: which credential your case needs.

People search for a tax debt attorney because "attorney" sounds like the heaviest tool available. Sometimes it is. Often the case belongs with an Enrolled Agent, and a firm that tells you otherwise is selling the title rather than the work. Here is the honest breakdown.

Licensed by a state bar

Tax attorney

A tax attorney is a licensed lawyer who practices tax. Attorneys, CPAs, and Enrolled Agents all have unlimited IRS representation rights, including administrative appeals. Tax Court representation requires separate admission to that court, which also admits qualifying nonattorneys. A tax attorney can advise on legal exposure and attorney-client privilege; privilege depends on the purpose and circumstances of the communication.

Strongest on: Tax Court petitions, appeals that turn on a legal argument, trust fund recovery penalty disputes, cases with fraud or criminal exposure, and any case where privilege matters.

Licensed by the U.S. Treasury

Enrolled Agent (EA)

An Enrolled Agent is licensed federally by the Treasury Department, either by passing the three-part Special Enrollment Examination or through qualifying IRS employment. An EA has the same unlimited right to practice before the IRS that an attorney has, in every state, and collection work is what EAs do all day.

Strongest on: Wage garnishment and bank levy releases, installment agreements, Offers in Compromise, Currently Not Collectible requests, penalty abatement, and transcript analysis.

Licensed by a state board

CPA

A Certified Public Accountant is licensed by a state board of accountancy and also holds unlimited practice rights before the IRS. A CPA is the right credential when the problem is the return itself rather than the collection action attached to it.

Strongest on: Years of unfiled returns, amended returns, reconstructed business books, substitute-for-return replacements, and audits that hinge on documentation rather than law.

The short version: hire a tax attorney when there is a legal question inside your tax problem. A U.S. Tax Court petition after a Notice of Deficiency, a Collection Due Process appeal that turns on whether the IRS followed its own procedure, a trust fund recovery penalty the IRS wants to assess against you personally, an audit where you would rather not explain a position without privilege, or anything that smells like criminal exposure. Those are attorney cases, and they are not close calls.

Everything else is usually collection work. A garnished paycheck, a frozen bank account, a balance you cannot pay, six years of returns you never filed. An Enrolled Agent has the same unlimited practice rights before the IRS that an attorney has, and this is the work EAs are licensed and tested specifically to do. Our case assignment follows the problem, which is why the first call is a diagnostic and not a pitch.

One note on the money, and then we will leave it alone: fees depend on the services your case actually requires and on its complexity, they are never a percentage of anything the IRS forgives, and they are explained to you before you decide anything. You can get that quote in the free consultation.

03 · Garnishment cases

When a wage garnishment needs a lawyer, and when it does not.

An IRS wage garnishment is a continuous levy. It does not run once and stop. It attaches to every paycheck until the balance is satisfied or the IRS releases it, and the amount exempt from an IRS wage levy follows the tables in IRS Publication 1494. The protected amount depends on factors such as filing status, dependents, and pay frequency.

1

File Form 2848 and take over IRS contact

After the engagement and signed authorization are in place, we submit Form 2848 for the matters your case covers. Once recognized by the IRS, your representative can request account transcripts and handle authorized IRS communications. You still receive notices, and the form can authorize copies to your representative; filing does not instantly redirect all IRS contact.

2

Check whether the CDP window is still open

The IRS generally must give you a Final Notice of Intent to Levy and Notice of Your Right to a Hearing, such as Letter 1058 or LT11, at least 30 days before a levy. Request a Collection Due Process hearing on Form 12153 by the deadline on the notice. A timely request generally suspends levy action for the covered periods while the hearing and any judicial review are pending. Statutory exceptions apply.

3

Put a collection alternative in front of the IRS

A representative reviews whether an installment agreement, Currently Not Collectible status, or an Offer in Compromise fits your situation, then requests levy release on the applicable grounds. A pending proposal generally limits new levies but does not automatically release an existing wage levy. Stopping the levy and resolving the underlying balance are related tasks.

4

Request release for economic hardship

Under IRC section 6343, the IRS must release a levy when it determines that the levy creates an economic hardship by preventing an individual from meeting reasonable basic living expenses. Be ready to document income and expenses with pay stubs, housing, utilities, and medical costs. The IRS may request Form 433-A or Form 433-F. Releasing a levy does not erase the debt.

5

Fix the compliance problem underneath it

Installment agreements and Offers in Compromise generally require all required returns to be filed. Missing returns should be addressed alongside the collection problem. However, hardship levy release and Currently Not Collectible hardship status may still be available when returns are unfiled; do not delay asking for hardship relief solely because filings are missing.

Timing is often the first question. We submit Power of Attorney after the engagement and signed authorization are complete, but filing it does not stop a garnishment. The IRS decides whether release criteria are met, including an applicable collection alternative or documented hardship. Your documents and IRS processing affect the timeline. We do not guarantee a filing turnaround or a levy release date.

What we can tell you is what shortens it. Have your last two pay stubs, your rent or mortgage, your utility and insurance costs, and a list of the years you did or did not file ready for the consultation. Cases where the client sends documents in the first week move differently from cases where they arrive in the second month.

Garnishment work sits inside our wage garnishment and IRS levy relief service, and the resolution that ends it is usually an IRS payment plan, Currently Not Collectible status, or an Offer in Compromise. If your income is Social Security rather than wages, the rules are different and we cover them in can the IRS garnish Social Security.

04 · Bank levies

Bank levies and the 21-day hold.

A bank levy works differently from a wage garnishment, and the difference is the only thing that matters when it happens to you. A wage levy is continuous. A bank levy is a snapshot. It grabs the balance sitting in the account on the day the bank processes the notice, freezes exactly that amount, and holds it for 21 days before wiring it to the IRS. Deposits that land after that day are not caught by that levy, though the IRS can and does issue another one.

The 21-day hold gives you time to contact the IRS about the levy before the bank sends the money. You can raise an error, explain ownership of the funds, or provide evidence that losing the money would prevent you from meeting basic living expenses. Contact the IRS or your authorized representative promptly; Form 2848 alone does not release the funds.

Inside the window, a representative can request a release under IRC section 6343 on hardship grounds, show that the levy was issued while an installment agreement or Offer in Compromise was pending, argue that the collection statute has expired on the year at issue, or establish a resolution that gives the IRS a reason to stand down. After the funds leave the bank, you may request return of the levy proceeds under separate eligibility rules and deadlines.

Bank levy releases are handled through the same IRS levy and bank levy release service as garnishments. If the IRS has also filed a Notice of Federal Tax Lien against you, that is a separate problem with a separate fix, covered in IRS tax lien help.

05 · Audits

When an audit needs an attorney rather than an EA.

People search for an IRS audit attorney the day the letter arrives, and the instinct is right even when the credential is not the deciding factor. The IRS runs three kinds of examination: correspondence audits handled entirely by mail, office audits where you report to an IRS location, and field audits where a revenue agent comes to your home or business. A correspondence audit usually asks you to supply records supporting specific items on the return.

An authorized representative can generally attend an examination interview for you. The IRS cannot require you to accompany that representative unless it issues an administrative summons. Your representative helps prepare complete, accurate responses and the supporting records. An examination can expand to other items or years when the IRS identifies related issues, so understanding the scope and deadlines matters.

Where a tax attorney specifically earns the call: an audit with fraud indicators, an eggshell audit where the return has a position you would rather discuss under privilege, an examiner threatening a referral, or an outcome you already know is heading to Appeals or U.S. Tax Court. Those cases start with an attorney and stay with one. A documentation audit, by contrast, is often best handled by the CPA or Enrolled Agent who can reconstruct the records fastest.

Our audit work lives at IRS audit help and audit defense, and the broader representation service at IRS tax representation. If you want to know what pulls a return in the first place, we wrote about what triggers an IRS audit.

06 · Field collection

Revenue Officer cases and field collection.

Most IRS collection is automated. Notices generate on a schedule out of the Automated Collection System, and nobody at the IRS is thinking about you personally. A Revenue Officer case is the opposite. A Revenue Officer is a human being in a local field office with your file on their desk, a caseload they are measured on, and authority to issue summonses, conduct field investigations, and recommend seizure. Routine unannounced Revenue Officer visits ended in 2023; appointments are generally arranged by letter, with limited exceptions.

Cases get assigned to field collection for a reason: a large balance, payroll tax debt, a pattern of unfiled returns, a defaulted installment agreement, or a business that kept operating while accruing new liabilities. Payroll cases can involve personal liability through the trust fund recovery penalty. The IRS must establish that a person was responsible for collecting, accounting for, or paying over the taxes and willfully failed to do so; a title or check-signing authority alone does not settle that question. The investigation may include a Form 4180 interview. If personal liability or legal exposure is at issue, discuss whether you need legal counsel before the interview.

When a Revenue Officer has already made contact, the first move does not change: Power of Attorney, then transcripts, then a financial statement on Form 433-A or 433-B that is accurate and defensible before it goes anywhere near the officer. Revenue Officers generally deal with representatives professionally, and a case that arrives organized is a case that gets a collection alternative considered instead of an enforcement step.

The one thing that does not work is silence. Missed deadlines with an assigned Revenue Officer are what turn a resolvable balance into a levy. If payroll taxes are part of your case, start with the most common payroll tax issues, and if returns are missing, unfiled tax returns is the first thing to fix.

07 · The engagement

What representation involves, and what you still do yourself.

Representation is a division of labor, not a disappearing act. Here is the split, plainly.

What we handle

  • Form 2848. Power of Attorney is filed for the tax types and years your case covers, which puts a credentialed representative on record with the IRS Centralized Authorization File.
  • Authorized IRS contact. We handle communications for the matters covered by your authorization, including Collections, Examination, and an assigned Revenue Officer. You may still receive notices or be required to participate.
  • Transcripts and diagnosis. We pull your full account transcripts, confirm what was actually assessed and for which years, and check where each collection statute expiration date sits.
  • The proposal. Financial statements, the collection alternative that fits your numbers, the filings, and the follow-up when the IRS asks for more.

What stays with you

  • Documents, on time. Pay stubs, bank statements, expense records, prior returns. Nothing moves faster than the file you send us.
  • Current-year compliance. Withholding or estimated payments have to be right going forward. Installment agreements and Offers in Compromise generally require current filing and payment compliance; hardship relief is assessed under separate rules.
  • Filing your returns. We prepare them; the legal duty to file remains yours. Form 2848 does not transfer that, and it does not transfer the liability.
  • The decisions. Which program to pursue is your call, made with our recommendation. The IRS makes the final determination on every one of them, and no representative can promise you an outcome.

08 · Due diligence

When to hire a tax attorney: what to check before you sign.

Tax resolution has a real problem with firms that sell hard and deliver little. Whether you end up hiring a wage garnishment attorney, an Enrolled Agent, or nobody at all, these five checks separate the two, and they work on us as well as on anyone else.

Ask which credential is actually going to work your file.

Attorney, CPA, and Enrolled Agent are the only three credentials with unlimited practice rights before the IRS. A salesperson is not one of them. Ask for the name and credential of the person who will sign your Form 2848, and verify it. Enrolled Agents can be confirmed through the IRS directory of federal tax return preparers; an attorney can be confirmed through the licensing state bar.

Be skeptical of any outcome promised before transcripts are pulled.

Nobody can tell you whether you qualify for an Offer in Compromise, or how a garnishment will resolve, before reviewing your IRS account transcripts and your actual finances. A firm that promises a settlement figure on the first call is describing a sales script, not your case.

Walk away from percentage-of-savings fees.

Tax resolution work should never be billed as a cut of what the IRS forgives. That structure gives the firm a reason to oversell the outcome. Innovative Tax Relief does not charge based on a percentage of savings or debt reduction.

Get the scope in writing before you sign anything.

The engagement should say which years are covered, which returns are being prepared, which program is being pursued, and what happens if the IRS rejects the first proposal. Vague scope is where tax resolution complaints come from.

Read the reviews and check the accreditation.

Look for reviews that describe the process rather than the outcome, and check whether the firm is accredited and how it responds to complaints. Our credentials and accreditations are published, and so are hundreds of client reviews.

Ours are published: see our accreditations and IRS credentials and our verified client reviews.

$ 0 M+
in tax debt resolved
0 +
clients helped
0 + years
avg. experience per tax pro

† Internal company figures through 2026. Tax debt addressed on behalf of clients. Individual results vary by case and IRS or state agency review.

Federal programs

The resolutions a garnishment case usually ends in.

A wage garnishment is a symptom. These are the federal programs that treat the balance underneath it, and the first thing a wage garnishment attorney or Enrolled Agent does is work out which one your numbers support. The IRS Fresh Start Program expanded access to several of them.

Frequently asked

Wage garnishment attorney and IRS representation FAQ.

The questions we hear most about hiring a tax attorney, releasing a garnishment or levy, and what Form 2848 actually does.

Do I need a wage garnishment attorney to stop an IRS wage garnishment?

Not necessarily. A wage garnishment attorney, a CPA, and an IRS Enrolled Agent all hold unlimited rights to represent you before the IRS, and most garnishment releases are won by documenting a collection alternative rather than by making a legal argument. An attorney becomes the right choice when the case involves a Tax Court petition, a contested appeal, trust fund recovery penalties, or possible criminal exposure. At Innovative Tax Relief the credential is matched to the case at the free consultation.

Are tax attorneys worth it for IRS tax debt?

A tax attorney is worth it when your case has a legal question in it: a U.S. Tax Court petition, a Collection Due Process appeal that turns on the law, a trust fund recovery penalty assessment against you personally, an eggshell audit, or anything with criminal exposure. If the case is ordinary collection work on an ordinary balance, an Enrolled Agent has the same practice rights before the IRS and does that work every day. The honest answer is that the credential should follow the problem.

What is the difference between a tax attorney, a CPA, and an enrolled agent?

All three have unlimited rights to represent clients before the IRS, including audits, collections, and administrative appeals. A tax attorney is a licensed lawyer who can advise on legal exposure and privilege. Tax Court representation requires separate court admission, including for attorneys. An Enrolled Agent is federally licensed, while a CPA is licensed by a state board. Specialties vary, so ask about relevant case experience. Some uncredentialed preparers have limited representation rights; others have none, and neither group can represent clients in IRS collection matters.

How fast can an IRS wage garnishment be released?

A representative can submit Form 2848 after receiving the signed authorization, but IRS processing and levy release are separate steps. Filing the form does not immediately stop a levy or all contact with you. The IRS decides whether a release ground applies, including documented economic hardship under IRC section 6343. Timing depends on the case, IRS processing, and the documents needed, so we do not promise a release date.

Can a tax debt attorney release a bank levy during the 21-day hold?

A representative may request release during the 21-day bank hold, but release is not guaranteed. The bank generally holds the funds subject to the levy for 21 days before sending them to the IRS. Contact the IRS or your authorized representative promptly to discuss hardship or another release ground. After payment, you may still be able to request return of the proceeds under separate rules and deadlines.

Do I need an IRS audit attorney for a correspondence audit?

Usually not. Most correspondence audits are document requests that are answered in writing, and a CPA or Enrolled Agent can handle that exchange. An IRS audit attorney matters when the audit could expand into other years, when the examiner raises fraud indicators, when the return has a position you would rather not explain without privilege, or when the audit result is headed for appeal or Tax Court.

What is IRS Form 2848 and what does it let my representative do?

Form 2848, Power of Attorney and Declaration of Representative, authorizes a credentialed representative to act for you before the IRS on the tax types and years you list. It lets them receive notice copies if authorized, pull your account transcripts, speak with Collections and Examination, negotiate a resolution, and sign certain agreements. It does not transfer your legal responsibility to file returns or to pay what is owed.

Is Innovative Tax Relief a law firm?

No. Innovative Tax Relief is a tax resolution firm, not a law firm, and hiring us does not create an attorney-client relationship unless a separate written agreement says so. Our team includes tax attorneys, CPAs, and IRS Enrolled Agents, and those professionals represent you before the IRS under federal practice rights that apply in all 50 states.

Verified review · Google

Pablo is pretty awesome, keeps me updated through out the whole process, works with me through my crazy schedule, very helpful with info and questions. Highly recommend
PC
Paul C. Verified Google review
Aug 2026
It's been very awesome Josh Molina was very attentive and explained and made sure that I understood the process, I recommend his service. Thank you Josh
Melquiades S. · Google review
Aug 2026
My whole experience has been great. Excellent service. Pablo has been great with keeping me informed how everything is proceeding. Thank you Pablo for everything you and all staff have done.
George M. · Google review
5.0 / 5
Google rating
0+
Verified reviews

Wages garnished, account frozen, or an audit letter on the table?

Free consultation with our team. No obligation.

Straight from the IRS

Everything on this page traces back to these IRS sources. They are what we work from every day.

Links verified2026-08-26. irs.gov · taxpayeradvocate.irs.gov

Call Free consultation